Bridging Wealth, Values, and Generations: Estate Planning Is Never Just About Numbers
Talking about "inheritance" at the family dinner table still feels awkward for a lot of Indonesian families. Bring it up too early, and you risk sounding greedy—or worse, like you're wishing something bad on parents who are perfectly healthy. So the topic gets shelved, usually until it can't be avoided anymore: at the funeral.
Here's the irony. It's precisely that silence—and the lack of proper planning—that ends up wrecking family relationships and eroding wealth that took a lifetime to build.
There's a line from Sanjay Tolani, a well-known voice in estate planning circles, that sums it up well:
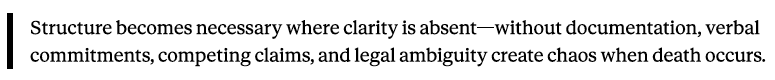
So the real question is: how do you plan an inheritance so that what you leave behind becomes a blessing, not a family feud?
1. Two Things People Mix Up: Inheritance vs. Legacy
The most common mistake is treating "legacy" as purely material. In reality, there are two dimensions, and they're meant to work together.
Inheritance (Wealth) is what you leave to someone—cash, land, property, shares, a business. It's tangible and concrete. Think of it as fuel: it moves things forward, but it doesn't decide the direction.
Legacy (Values) is what you leave in someone—character, integrity, mindset, habits, a sense of purpose. If wealth is the fuel, legacy is the compass—it's what determines where the vehicle actually goes.
The formula is simple:
Healthy Wealth Transition = Values (Legacy) + Assets (Inheritance)
Think of it this way: handing over wealth without values is like handing a race car to someone who's never driven before. Sooner or later, something crashes—the assets, the relationships, or both. This is part of what people call the "third-generation curse," where wealth built by the first generation often disappears by the time it reaches the third.
On the flip side, values without any wealth aren't ideal either—the next generation ends up starting from zero when the resources to give them a head start already existed. Combine the two, and you get a multiplier effect: resources managed with a clear moral compass behind them.
2. What Happens Without a Plan
Without legal documents and proper planning in place, families are left to navigate what we might call a "friction zone"—and it's expensive, both emotionally and financially.
Assets freeze immediately. The moment an asset owner passes away, bank accounts and investment access get locked until legal proof of inheritance is established.
Legal and religious gaps can spark real conflict. Without a clear will, the application of inheritance law—Faraidh, for instance—can produce outcomes that feel deeply unfair to some family members. A family with no sons might see the majority of the estate go to the deceased's siblings, while the wife and daughters receive only a small share. These situations are exactly what drive costly, emotionally draining legal disputes.
What's received is never what was left. There's "leakage" along the way: outstanding debts, medical costs before death, property transfer tax, notary fees. Without liquid cash on hand, families are often forced to sell property below market value just to cover the gap—a fire sale, essentially.
3. The Legal Toolkit in Indonesia: SKW and Legitime Portie
Estate planning in Indonesia still has to work within existing legal boundaries, or it risks being invalidated entirely.
- Surat Keterangan Waris (SKW) — the official document needed to unlock bank accounts and transfer property titles. Without it, the asset freeze drags on indefinitely.
- Legitime Portie — under Indonesian Civil Law (BW), direct-line heirs (children, parents) are entitled to a fixed minimum share that a will cannot reduce or override.
- Life insurance as the gap-filler — since Indonesia's legal system doesn't recognize trusts the way some other countries do, life insurance effectively becomes the bypass. The payout goes straight to the named beneficiary, in cash, without waiting for accounts to unfreeze—so it can immediately cover debts and taxes.
4. A Working Framework: The 3 Pillars of Estate Planning
To turn all of this into something actionable, families can build around three pillars.
Pillar 1 — Estate Planning: Preparing the Assets
Getting the legal structure and asset inventory in order, preparing the SKW, a notarized will, or a deed of gift, and making sure the family business still has one clear operational leader—even if share ownership is split equally among the children.
Pillar 2 — Risk Management: Securing the Value
Setting aside liquid funds to cover leakage (debts, medical costs, taxes), preventing forced fire sales of assets, and establishing guardianship for heirs who are minors or otherwise vulnerable.
Pillar 3 — Legacy Planning: Preparing the People
Opening up honest, transparent family conversations, mentoring the next generation on financial literacy and leadership, and—most importantly—agreeing together on what "fair" actually means for this family, so relationships stay intact.
Closing Thought: The Process Itself Is the Most Valuable Inheritance
Here's the thing: inheritance disputes are rarely about the actual numbers. What usually drives them is a feeling of unfairness that was never talked through.
Estate planning was never really about planning for death. It's about building an emotional bridge between a lifetime of a parent's hard work and the real needs and capacity of their children.
Estate Planning prepares the assets. Risk Management secures the value. Legacy Planning prepares the people, through the experience of sitting down together.
Physical wealth fades with time. But the memory of openness, togetherness, and fairness while planning it all together—that's the legacy that keeps living on through the generations that follow.